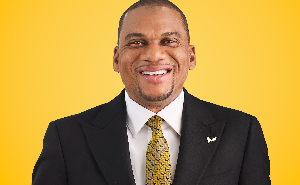
 Farihan Alhassan, Managing Director of GCB Bank PLC
Ghana’s lower-rate cycle is forcing banks to prove that growth can be sustained without the unusually high yields of recent years. Nine months into 2026, GCB Bank’s results suggest that the franchise is finding that balance: earnings accelerated even as interest income barely moved, while lending expanded sharply alongside improving asset quality.
For the nine months to September 2026, operating income rose 32.4 per cent year-on-year to GH¢5.70 billion, while profit before tax increased 42.6 per cent to GH¢2.87 billion. Profit after tax climbed 44.0 per cent to GH¢1.86 billion, lifting earnings per share to GH¢9.38 from GH¢6.51 a year earlier.
The more important story is the composition of that growth. Interest income increased by just 1.3 per cent to GH¢4.39 billion, reflecting the pressure from lower market rates. However, interest expense fell by nearly a third to GH¢816 million, allowing net interest income to rise 14.0 per cent year-on-year to GH¢3.57 billion.
The stronger boost came from non-funded income. Net fee and commission income rose 87.4 per cent to GH¢1.07 billion, while trading income increased 71.6 per cent to more than GH¢1.0 billion. Together, non-funded income contributed about 37 per cent of operating income, up from roughly 27 per cent a year earlier. This ten-percentage-point shift is significant in an environment where traditional interest margins are under pressure.
The shift matters because it aligns with the Bank’s publicly stated push to broaden its revenue sources and build a more diversified earnings base beyond traditional interest income. This is vital as lower yields and tighter margins test the sector’s earnings resilience.
Operating efficiency improved alongside revenue growth. Personnel, depreciation and other operating expenses grew more slowly than income, lowering the cost-to-income ratio to about 45.1 per cent from 49.2 per cent a year earlier.
The balance sheet also expanded strongly. Customer deposits grew 22.8 per cent to GH¢50.88 billion from December 2025, providing the funding capacity for net loans and advances to rise 57.3 per cent to GH¢25.23 billion. Investment securities increased 21.1 per cent to GH¢19.80 billion, while total assets expanded 29.0 per cent to GH¢67.62 billion.
The direction is clear. GCB is allocating more of its balance sheet to drive credit expansion and support the real economy. This broadly mirrors the industry’s shift back towards private-sector lending as asset quality improves. For context, the industry’s loan book grew by 16.4 per cent year-to-August, with real growth in private-sector credit also remaining firm at 13.05 per cent. GCB’s pace of loan growth has therefore been considerably stronger than the sector average.
The quality of that expansion is equally important. The non-performing loans (NPLs) ratio fell to 4.8 per cent from 10.8 per cent a year earlier, compared with an industry ratio of 15.7 per cent in August. This is a favourable asset-quality signal, although the pace of loan-book growth makes subsequent impairment performance equally important to monitor.
Commenting on the results, Managing Director Farihan Alhassan said the lower-interest-rate environment was forcing banks to return to commercial banking fundamentals.
“The operating environment is demanding that banks do the hard work of banking – understand customers better, price risk appropriately, mobilise funding efficiently, and deploy capital into productive opportunities. At GCB, we are committed to winning the right way: helping fund the ambitions of Ghanaian businesses and entrepreneurs while maintaining disciplined underwriting and strong risk standards.”
He said the next priority was to build greater resilience into the Bank’s loan portfolio as economic and interest-rate cycles evolve.
“Our focus is not simply on growing the loan book. It is about building a portfolio that can perform through cycles – supporting today’s growth drivers while positioning GCB to finance the businesses and sectors that will shape Ghana’s next phase of growth.”
Alhassan expressed confidence in the Bank’s strategy, saying its focus remained on delivering greater value to customers and providing solutions that meet the needs of businesses, households and the wider economy.
However, the expansion is consuming balance-sheet capacity, as expected. Impairment charges rose to GH¢260 million, capital adequacy eased to 14.6 per cent from 16.2 per cent a year earlier, and the liquidity ratio declined to 64.3 per cent from 73.4 per cent over the same period. None of these figures currently signals distress, but the direction matters: rapid credit growth consumes capital and liquidity, placing a premium on disciplined underwriting and balance-sheet management.
The outlook therefore cuts both ways. Lower rates and resilient domestic activity should support credit demand and transaction volumes, while a broader earnings mix gives GCB more than one engine for growth. However, the same operating environment places a premium on disciplined underwriting, capital management and liquidity control.
Nine months into 2026, the numbers point to a more credit-driven GCB with a broader earnings base than a year ago. That is a meaningful shift in a lower-rate environment. The next test is whether the Bank can sustain this mix of credit growth and non-funded income without allowing capital consumption, liquidity pressures or credit costs to dilute earnings quality.
Copyright © 1994 - 2026 GhanaWeb. All rights reserved.